

Built by the team behind the #1 SBA lender in the US.
Built by the team behind the #1 SBA lender in the US.
Built by the team behind the #1 SBA lender in the US.
Built by the team behind the #1 SBA lender in the US.
Built by the team behind the #1 SBA lender in the US.
Close more loans with the team you [i]have.[/i]
Close more loans with the team you [i]have.[/i]
Close more loans with the team you [i]have.[/i]
Close more loans with the team you [i]have.[/i]
Close more loans with the team you [i]have.[/i]
Win more of the right loans with faster decisions.
Win more of the right loans with faster decisions.
Win more of the right loans with faster decisions.
Win more of the right loans with faster decisions.
Win more of the right loans with faster decisions.
Agents keep every file moving, so your borrowers get an answer while other banks are still chasing documents.
Underwrite faster, with every figure tied to its source.
Underwrite faster, with every figure tied to its source.
Underwrite faster, with every figure tied to its source.
Underwrite faster, with every figure tied to its source.
Underwrite faster, with every figure tied to its source.
Agents spread financials on arrival and draft the credit memo, so your underwriters spend their time on the credit decision.
Grow your lending business without growing headcount.
Grow your lending business without growing headcount.
Grow your lending business without growing headcount.
Grow your lending business without growing headcount.
Grow your lending business without growing headcount.
Agents carry the routine work across the pipeline, so each lender can handle more deals with the same hours.
*Results from Praxent clients.
The engine sits on top of your core, loan origination system and [i]CRM.[/i]
The engine sits on top of your core, loan origination system and [i]CRM.[/i]
The engine sits on top of your core, loan origination system and [i]CRM.[/i]
The engine sits on top of your core, loan origination system and [i]CRM.[/i]
The engine sits on top of your core, loan origination system and [i]CRM.[/i]
Your lenders keep the systems they know. Agents read from them, and anything they write back waits for a person to approve it.
Watch the engine work a commercial loan from documents to [i]approval.[/i]
Watch the engine work a commercial loan from documents to [i]approval.[/i]
Watch the engine work a commercial loan from documents to [i]approval.[/i]
Watch the engine work a commercial loan from documents to [i]approval.[/i]
Watch the engine work a commercial loan from documents to [i]approval.[/i]
Agents work the pipeline, and your lenders approve every [i]decision.[/i]
Agents work the pipeline, and your lenders approve every [i]decision.[/i]
Agents work the pipeline, and your lenders approve every [i]decision.[/i]
Agents work the pipeline, and your lenders approve every [i]decision.[/i]
Agents work the pipeline, and your lenders approve every [i]decision.[/i]
Agents gather documents, spread financials, draft credit memos, cross-check wires and catch exceptions before closing. Each one is built on your bank's own process, policies and templates.
Gathers every document as it arrives.
Gathers every document as it arrives.
Gathers every document as it arrives.
Gathers every document as it arrives.
Gathers every document as it arrives.
The agent reads each file that lands in the loan folder, checks it against your list and requests missing documents from the borrower. Nobody tracks documents in a spreadsheet again.
Files reach underwriting complete and sooner.
Spreads financials the moment they land.
Spreads financials the moment they land.
Spreads financials the moment they land.
Spreads financials the moment they land.
Spreads financials the moment they land.
The agent pulls revenue, cash flow and debt from tax returns and statements into your spread template, then calculates DSCR and leverage against your credit policy.
Underwriters start with the analysis done.
Drafts the credit memo in your format.
Drafts the credit memo in your format.
Drafts the credit memo in your format.
Drafts the credit memo in your format.
Drafts the credit memo in your format.
The agent writes the loan committee memo from your template, with every figure linked to the document it came from. Your lender reviews, edits and approves it.
Committee-ready memos in a fraction of the time.
Cross-checks every wire before it goes out.
Cross-checks every wire before it goes out.
Cross-checks every wire before it goes out.
Cross-checks every wire before it goes out.
Cross-checks every wire before it goes out.
The agent compares the wire request with the title company's wiring instructions and settlement statement: the amount to the cent, file number, routing and account numbers, beneficiary and property. It never releases a wire. Your team does.
Wire errors caught before the money moves.
Catches exceptions before closing.
Catches exceptions before closing.
Catches exceptions before closing.
Catches exceptions before closing.
Catches exceptions before closing.
The agent checks names, amounts, dates and addresses across every document in the file, so the typos that sink closings get fixed while there's still time.
Clean closings and fewer last-minute delays.
Watch the agents work the pipeline and approve every decision.
Watch the agents work the pipeline and approve every decision.
Watch the agents work the pipeline and approve every decision.
Watch the agents work the pipeline and approve every decision.
Watch the agents work the pipeline and approve every decision.
Lenders see the agents working the pipeline in a dashboard and approve every decision. Each approval shows the inputs, sources and confidence behind it.
Lenders spend their day on borrowers and credit calls.
Stop teaching your competitors how to lend like [i]you.[/i]
Stop teaching your competitors how to lend like [i]you.[/i]
Stop teaching your competitors how to lend like [i]you.[/i]
Stop teaching your competitors how to lend like [i]you.[/i]
Stop teaching your competitors how to lend like [i]you.[/i]
Software vendors
Software vendors
Software vendors
Software vendors
Software vendors
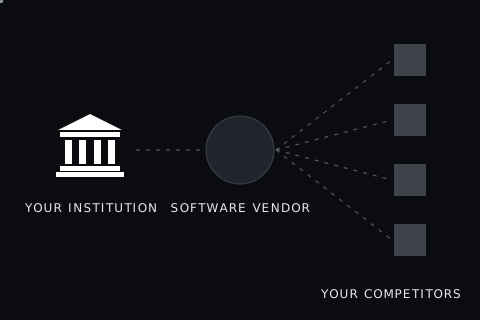
Your expertise trains their product.
Your expertise trains their product.
Your expertise trains their product.
Your expertise trains their product.
Your expertise trains their product.
Every file you process improves a vendor's model. They sell it to your competitors at full price.
Your bank on AgentCommand[sm]
Your bank on AgentCommand[sm]
Your bank on AgentCommand[sm]
Your bank on AgentCommand[sm]
Your bank on AgentCommand[sm]
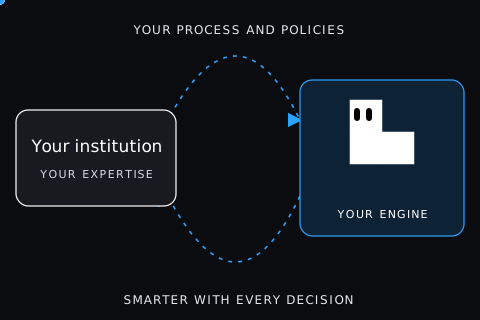
Your expertise compounds for you.
Your expertise compounds for you.
Your expertise compounds for you.
Your expertise compounds for you.
Your expertise compounds for you.
Every decision stays in engines you own, in your cloud. The advantage builds every quarter, and nobody else gets it.
Turn decades of lending expertise into proprietary agents, with every loan building intelligence your competitors can't [i]buy.[/i]
Turn decades of lending expertise into proprietary agents, with every loan building intelligence your competitors can't [i]buy.[/i]
Turn decades of lending expertise into proprietary agents, with every loan building intelligence your competitors can't [i]buy.[/i]
Turn decades of lending expertise into proprietary agents, with every loan building intelligence your competitors can't [i]buy.[/i]
Turn decades of lending expertise into proprietary agents, with every loan building intelligence your competitors can't [i]buy.[/i]
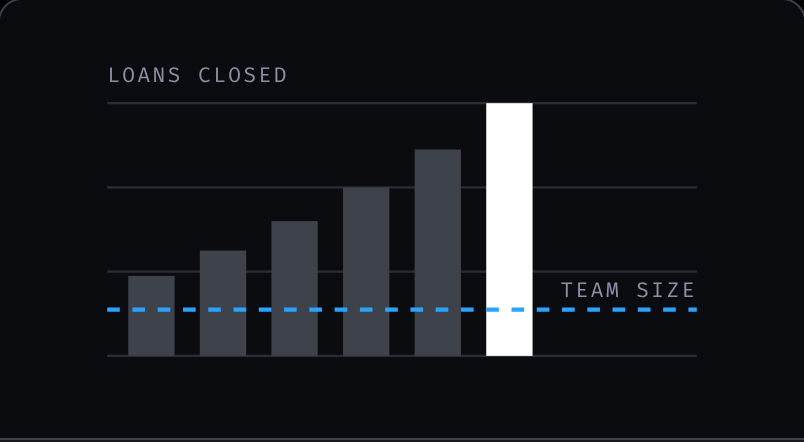
Lending growth
Lending growth
Lending growth
Lending growth
Lending growth
Borrowers choose the lender who replies first. Faster decisions win more of the right loans, and every loan you win grows your net interest income.
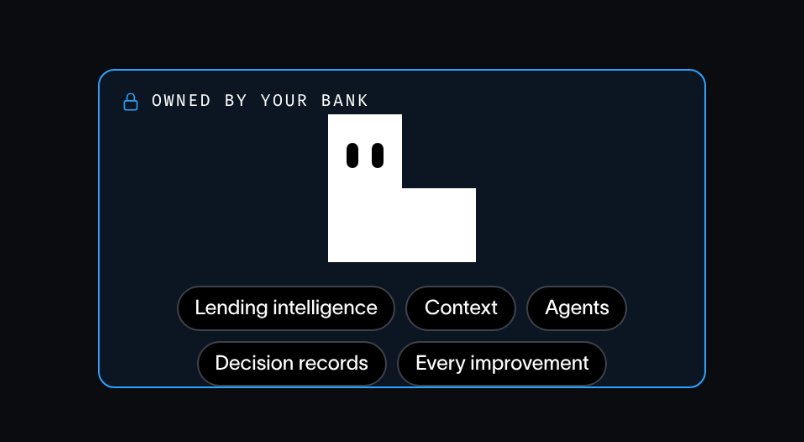
Proprietary agents
Proprietary agents
Proprietary agents
Proprietary agents
Proprietary agents
Turn decades of your institutional lending expertise into proprietary agents that enable you to decouple lending growth from underwriter headcount.
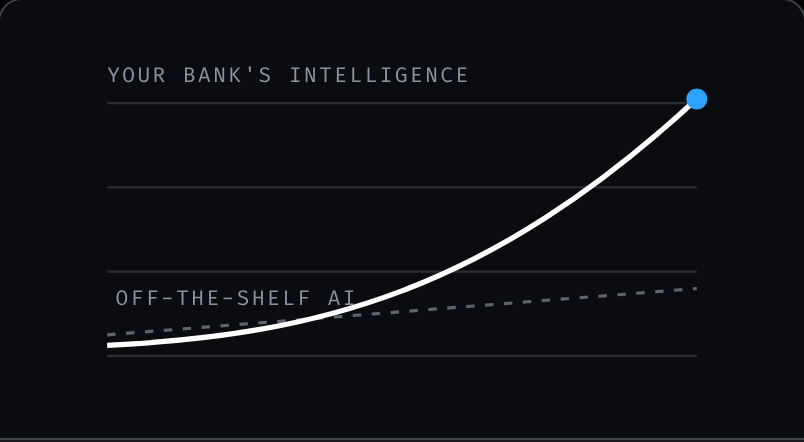
Compounding competitive value
Compounding competitive value
Compounding competitive value
Compounding competitive value
Compounding competitive value
Every lending decision makes your bank smarter, creating advantage your competitors can't buy.
Built for every loan in your commercial [i]book.[/i]
Built for every loan in your commercial [i]book.[/i]
Built for every loan in your commercial [i]book.[/i]
Built for every loan in your commercial [i]book.[/i]
Built for every loan in your commercial [i]book.[/i]
Each loan type gets agents shaped to its own documents, policy checks and closing conditions.
Owner-occupied CRE
Owner-occupied CRE
Owner-occupied CRE
Owner-occupied CRE
Owner-occupied CRE
Rent rolls, appraisals, environmental reports and DSCR against your CRE policy.
Investor CRE
Investor CRE
Investor CRE
Investor CRE
Investor CRE
Rent rolls, leases, global cash flow and concentration limits.
Multifamily
Multifamily
Multifamily
Multifamily
Multifamily
Unit mix, rent rolls, operating statements and debt yield against policy.
Construction
Construction
Construction
Construction
Construction
Budgets, draw schedules, inspections and completion risk.
C&I term loans
C&I term loans
C&I term loans
C&I term loans
C&I term loans
Business tax returns, interim financials, covenants and guarantor support.
Lines of credit
Lines of credit
Lines of credit
Lines of credit
Lines of credit
Borrowing base certificates, AR aging and annual renewals.
Equipment finance
Equipment finance
Equipment finance
Equipment finance
Equipment finance
Invoices, titles, UCC filings and collateral values.
SBA 7(a)
SBA 7(a)
SBA 7(a)
SBA 7(a)
SBA 7(a)
Eligibility, SBA forms, credit elsewhere tests and the full E-Tran package.
SBA 504
SBA 504
SBA 504
SBA 504
SBA 504
CDC coordination, interim financing, appraisal and the debenture closing.
Agricultural
Agricultural
Agricultural
Agricultural
Agricultural
Production records, crop insurance, farmland collateral and seasonal cash flow.
Start with commercial credit and extend to any financial [i]workflow.[/i]
Start with commercial credit and extend to any financial [i]workflow.[/i]
Start with commercial credit and extend to any financial [i]workflow.[/i]
Start with commercial credit and extend to any financial [i]workflow.[/i]
Start with commercial credit and extend to any financial [i]workflow.[/i]
The Commercial Lending Engine runs on AgentCommand[sm], Praxent's agent accelerator. AgentCommand[sm] can be extended to add new engines and power any financial workflow your institution wants to tackle.
Commercial Lending Engine
Mortgage Lending Engine
Consumer Lending Engine
Auto Lending Engine
Collections and Recoveries Engine
Deposit Operations Engine
Treasury Operations Engine
BSA/AML Engine


60 agents in production for the [i]#1 SBA loan facilitator.[/i]
60 agents in production for the [i]#1 SBA loan facilitator.[/i]
60 agents in production for the [i]#1 SBA loan facilitator.[/i]
60 agents in production for the [i]#1 SBA loan facilitator.[/i]
60 agents in production for the [i]#1 SBA loan facilitator.[/i]
NEWITY partnered with Praxent to build their SBA and small business loan platform from the ground up. With a hyper focus on speed to fund and getting agents into production, in 2025 NEWITY ranked as the #1 SBA loan facilitator in the country.
Your team governs every decision, and it all runs in your [i]cloud.[/i]
Your team governs every decision, and it all runs in your [i]cloud.[/i]
Your team governs every decision, and it all runs in your [i]cloud.[/i]
Your team governs every decision, and it all runs in your [i]cloud.[/i]
Your team governs every decision, and it all runs in your [i]cloud.[/i]
Agents suggest and your team approves.
Agents suggest and your team approves.
Agents suggest and your team approves.
Agents suggest and your team approves.
Agents suggest and your team approves.
Nothing is auto-approved below 0.90 confidence, and every step is logged with its inputs, sources, model, confidence, rule and approver, which also gives you a head start on model-risk documentation.
Suggests the action
Below 0.90 confidence goes to a person
Approves, edits or rejects
Your subscription, your code, your decision records.
Your subscription, your code, your decision records.
Your subscription, your code, your decision records.
Your subscription, your code, your decision records.
Your subscription, your code, your decision records.
Claude through your existing Azure AI Foundry resource
OpenID Connect, tested with Entra ID
Append-only event log with tamper-resistant tables
OpenTelemetry to Application Insights
Share the engine with your credit committee and your [i]CIO.[/i]
Share the engine with your credit committee and your [i]CIO.[/i]
Share the engine with your credit committee and your [i]CIO.[/i]
Share the engine with your credit committee and your [i]CIO.[/i]
Share the engine with your credit committee and your [i]CIO.[/i]

Commercial Lending Engine one-pager
Commercial Lending Engine one-pager
Commercial Lending Engine one-pager
Commercial Lending Engine one-pager
Commercial Lending Engine one-pager
What it does, the outcomes for your lenders and the NEWITY proof, on one page for your next leadership meeting.
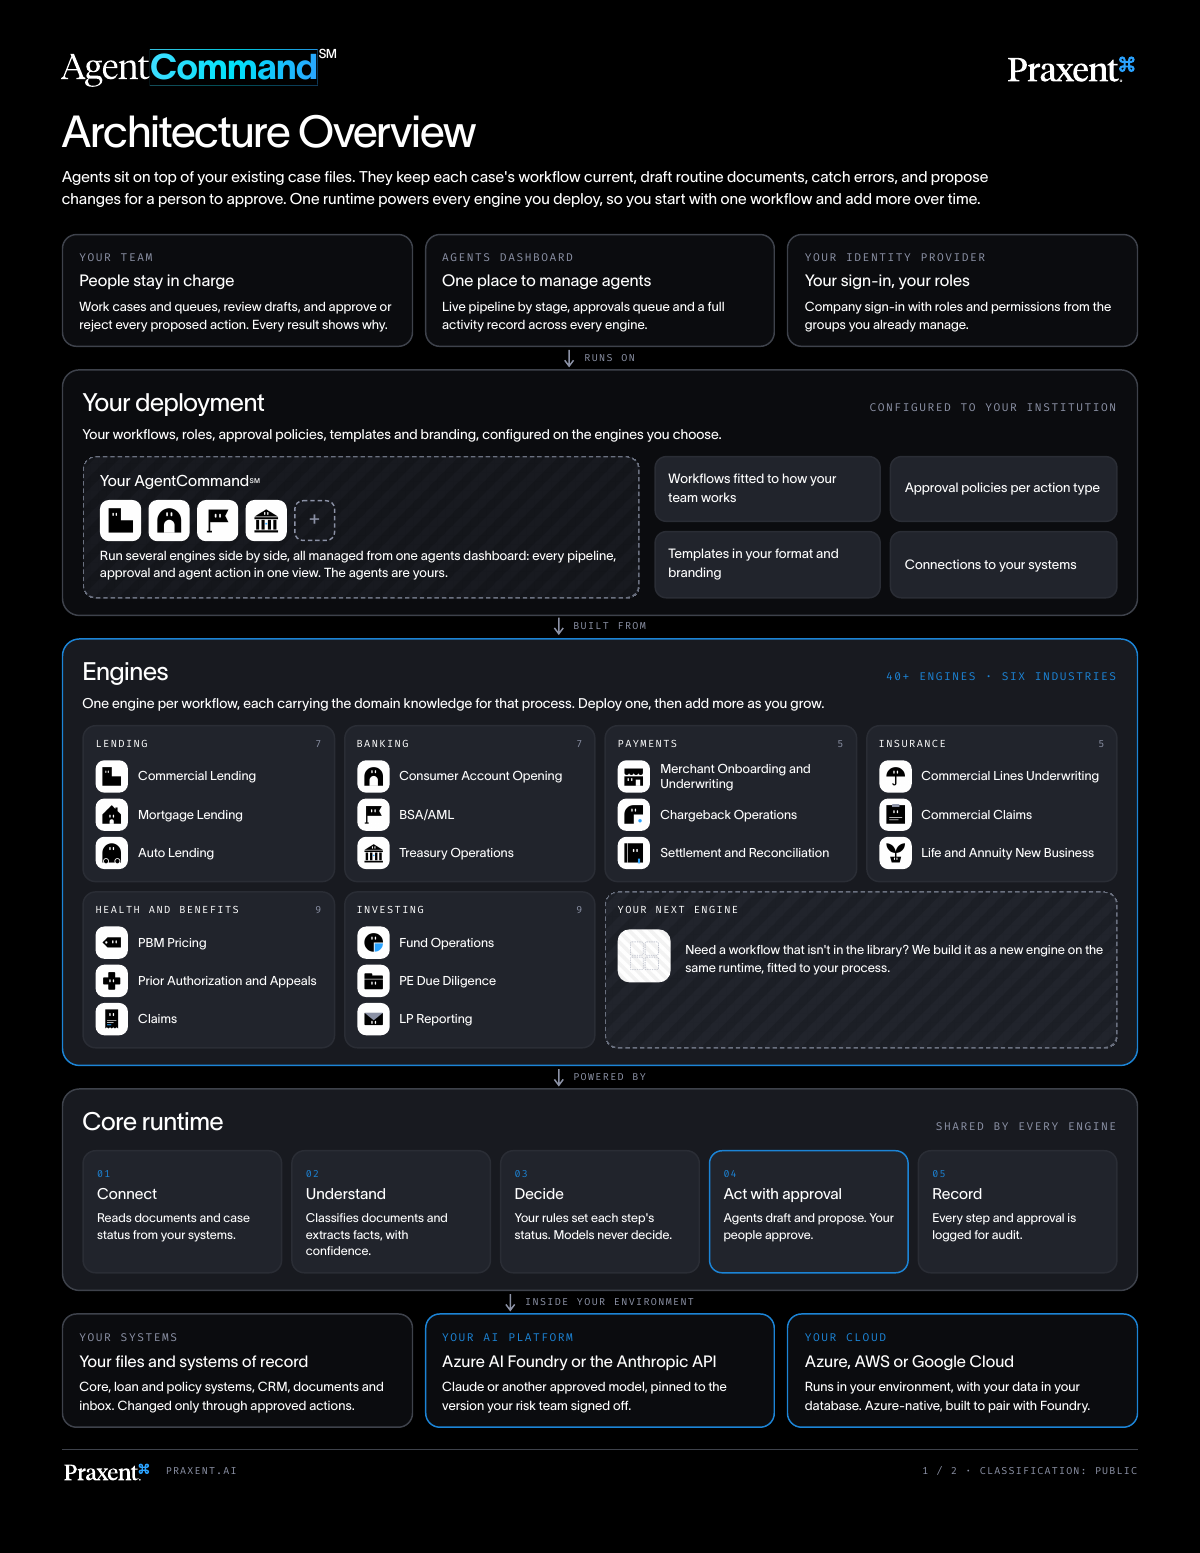
AgentCommand[sm] tech specs
AgentCommand[sm] tech specs
AgentCommand[sm] tech specs
AgentCommand[sm] tech specs
AgentCommand[sm] tech specs
Architecture, deployment, approval policies, audit tables and model access, for your CIO, head of AI and security team.
Agentic commercial lending strategy for 2027
Agentic commercial lending strategy for 2027
Agentic commercial lending strategy for 2027
Agentic commercial lending strategy for 2027
Agentic commercial lending strategy for 2027
Where agents fit in commercial credit, what your bank should own and how to start. We'll also show the Commercial Lending Engine working a commercial loan, live.